Revenue shows that customers have paid for an offer. It does not show that the offer is economical to deliver. A Whop business with losses can still be considered for sale, but the buyer needs to understand which costs are unavoidable and which changes are merely possibilities.
Rebuild one consistent operating period
Choose dates and a currency, then reconcile revenue after refunds with the costs of serving those customers. Include content production, moderators, contractors, software, hosting, payment fees and customer acquisition. Keep personal withdrawals separate from actual business expenses. Do not call the amount deposited into a bank account revenue without checking deductions and timing. Do not treat refunds twice: once inside net revenue and again as a separate expense. Explain your treatment so a buyer can reproduce the calculation.
Count the work the owner currently contributes
Free founder labour is not free to every buyer. List recurring tasks and hours, then distinguish cash expenses already paid from any additional replacement cost. If a moderator salary already covers a task, do not subtract a second replacement allowance for the same work. Hypothetical example: net revenue is USD 2,000 per month and operating costs are USD 2,300, creating a USD 300 operating loss. A buyer who needs another USD 400 of founder replacement has an additional burden, not a hidden USD 400 saving. A plan to remove USD 700 of advertising is only attractive if revenue can survive without it.
Test each proposed saving
| Cost | Can it stop immediately? | What might be lost? |
|---|---|---|
| Acquisition advertising | Sometimes | New-member pipeline |
| Founder-led coaching | Only with an agreed substitute | The core customer promise |
| Unused software | Possibly | Confirm no hidden integration dependency |
| Member support | Rarely without a replacement | Service quality and fulfillment |
Show evidence for a saving already achieved. Label an untested saving as a scenario. Do not present the buyer’s hypothetical efficiency as your current profit.
Look at transferable value and obligations
A useful content library, recognizable brand, documented process or working software can matter. Check ownership and relevance before assigning a value. Original production cost is not necessarily resale value; an expensive course may need extensive updating. List annual memberships, refunds, outstanding contractor payments and support commitments. A buyer may inherit substantial work before collecting another renewal. The sale agreement should identify who carries that work and which assets or obligations are excluded.
Choose an honest asking-price basis
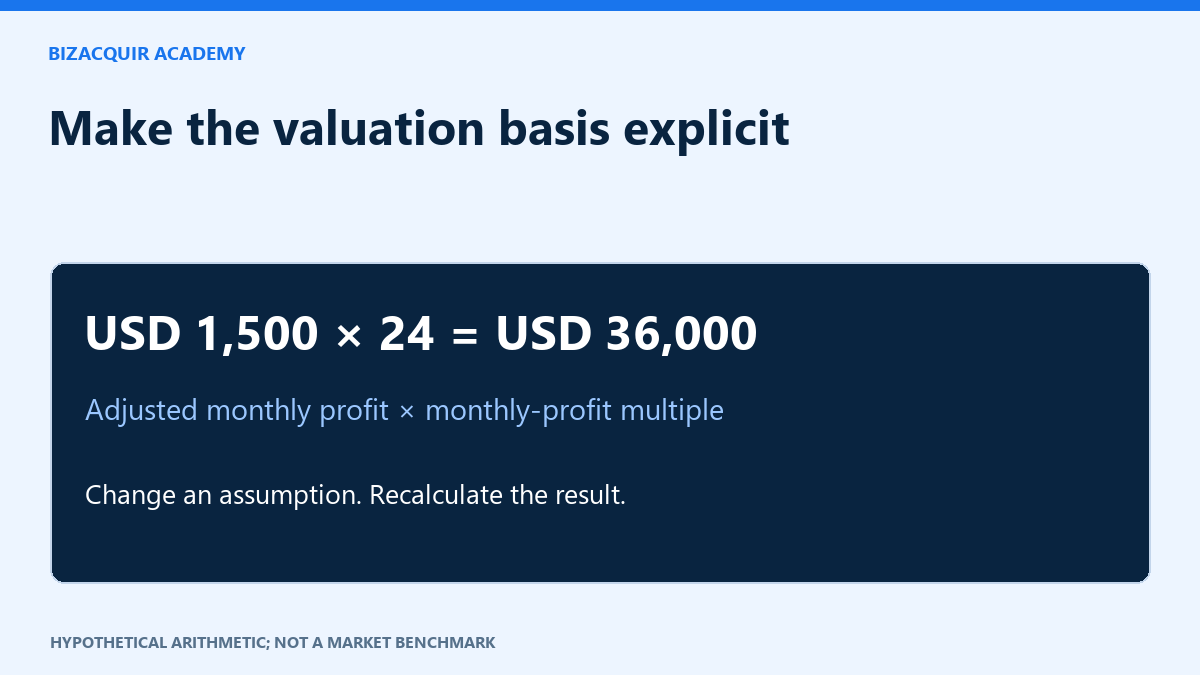
An earnings multiple is difficult to defend when maintainable earnings are zero or negative. Consider a supported asset-sale scenario and restart costs, and accept that the available information may not support a useful numerical range. Do not automatically multiply monthly revenue by three, four or five. Use BizAcquir’s valuation tool with the actual operating status and matching financial period, then review the result’s limitations. A valuation remains distinct from Asking Price. In the listing, explain the losses directly, connect the relevant revenue history and show what a buyer would actually receive. A lower, well-supported proposition can be more useful than a high headline built on imaginary cost cuts.
Check the relevant provider guidance
These official references support the platform-specific steps. Your own contracts, account configuration and agreed sale terms still need to be checked.
Explain losses with a bridge a buyer can inspect
Hypothetical month: revenue is $2,000, delivery and operating costs are $2,300, producing a $300 loss on that basis. Removing a $500 cost would show a $200 surplus only if the service still works and no replacement cost is needed. A proposed saving is not current profit.
Separate recurring costs, one-time work and owner labour. If the business is still operating, keep it Active even when loss-making. If trading actually stopped, state the inactivity date and show historical earnings separately. Neither case supports multiplying negative profit into a negative sale price.
Your next practical step
Use the WHOP selling checklist to turn the gaps into a preparation plan. You can start a private listing draft or explore a free valuation; signup or login is required to view valuation results.
Continue with How to Value a Whop Business: Factors, Examples and Limits and Can You Sell an Inactive Whop Business? What Buyers Evaluate.